Repository navigation
6.0.0

CDM Version 6.0
CDM 6.0, a production release, corresponds to developments made to the Common Domain Model throughout 2024 and previously released as CDM 6-dev. These developments include items that featured in the 2024 CDM roadmap:
- Option Payout Refactoring
- Asset Refactoring
- Standardized IM Schedule
as well as several additional model changes, bug fixes and synonym mappings since the latest production release (CDM 5.20).
What is being released
The release includes changes to the CDM model itself (manifested in changes to .rosetta source files) but also enhancements to:
- The CDM Documentation, which should be consulted as a good resource to understand the enhanced design of products and business events in CDM 6.
- The CDM Sample Files, which have been updated to reflect the new modelling designs.
- The CDM Object Builder, which can be used to construct CDM objects and generate JSON serialised data.
Below are some of the high-level modelling changes included in CDM 6.0, with links to their corresponding development release tags containing more detailed release notes.
Asset refactoring
A major feature of CDM 6 is the refactored product model with the introduction of the concept of Asset. This is the result of a CDM task force which came together to extend the model into additional asset classes and to address some long-standing challenges. The objectives and design artefacts of the task force were documented in GitHub Issue 2805.
This diagram shows the new product model at a high level; please read the FINOS CDM documentation for a full explanation:
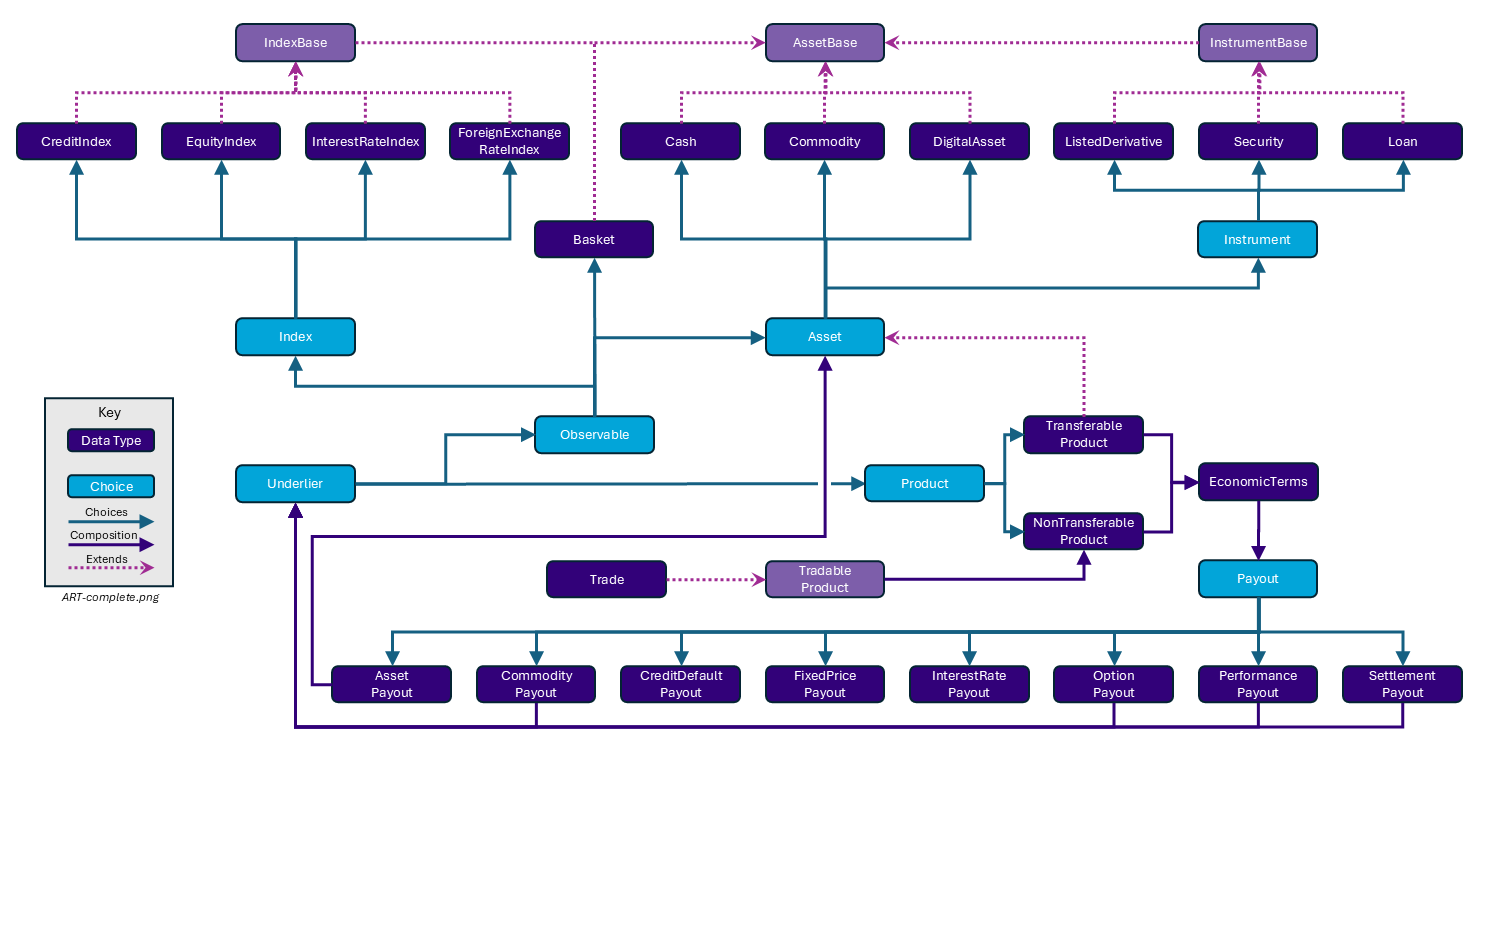
Individual releases related to asset refactoring:
- New Data Types: 6.0.0-dev.46
- Remove AssetPool and deprecated data types: Backward incompatible changes 6.0.0-dev.47
- Asset, Index, Identifier: Backward incompatible changes 6.0.0-dev.58
- Basket, Index, Observable, Foreign Exchange: Backward incompatible changes 6.0.0-dev.60
- Product, SettlementPayout, Underliers: Backward incompatible changes 6.0.0-dev.72
- Underlier in Corporate Action: 6.0.0-dev.77
- Payout as a Choice: Backward incompatible changes 6.0.0-dev.79
- ETD Product Qualification: 6.0.0-dev.79
- AssetCriteria: Backward incompatible changes 6.0.0-dev.81
- Settlement Payout Price: Backward incompatible changes 6.0.0-dev.84.
- Note: this change is only backward-incompatible because it reverts the Add Price to Payouts change in 6.0.0-dev.77. The two changes are backward-compatible in aggregate.
- Security Finance trade types: Backward incompatible changes 6.0.0-dev.86
- FloatingRateIndex and InterestRateIndex: Backward incompatible changes 6.0.0-dev.87
- Cashflow Generation for Settlement Payout : 6.0.0-dev.89
- Commodity Payout Underlier: 6.0.0-dev.90
Option Payout refactoring
- Option Payout Refactoring: Backward incompatible changes 6.0.0-dev.24
- Modification of AmericanExercise Condition in ExerciseTerms: 6.0.0-dev.41
Standardized IM Schedule
- Implementation of the Standardized Schedule Method for Initial Margin Calculation: 6.0.0-dev.69
- Enhancement and Optimization of the Standardized Schedule Method: 6.0.0-dev.90
Misc. model changes
- Product model
- Day Count Fraction: RBA_Bond_Basis: Backward incompatible changes 6.0.0-dev.22
- Trigger type refactoring: 6.0.0-dev.42
- Principal Amount Conditions: 6.0.0-dev.43
- Portfolio Return Terms: Backward incompatible changes 6.0.0-dev.55
- Exotic Equity Products and Exercise Terms validation conditions: Backward incompatible changes 6.0.0-dev.88
- Qualification functions:
- Zero Coupon Swaps: 6.0.0-dev.13
- Bond Option and Forwards: 6.0.0-dev.32
- Event model
- Addition of new enumeration to AvailableInventory: 6.0.0-dev.36
- Eligible Collateral model
- Determination of the Party Roles: 6.0.0-dev.4
- CheckEligibilityResult cardinality fix: 6.0.0-dev.10
- CreditNotationMismatchResolutionEnum update: 6.0.0-dev.26
- New Attributes: 6.0.0-dev.48
- Collateral Criteria AND/OR Logic: 6.0.0-dev.90
- Eligible Collateral condition logic: 6.0.0-dev.95
- Addition of SpecificAsset to CollateralCriteria: 6.0.0-dev.96
- Base model
- Natural Person and NaturalPersonRole circular reference: Backward incompatible changes 6.0.0-dev.3
- RoundToPrecision Function: 6.0.0-dev.40 & 6.0.0-dev.74
FpML mappings
- Synonym mappings for BusinessCenterEnum: 6.0.0-dev.33
Backward-incompatible changes
Asset refactoring
Main changes using the choice data type
A new feature in the Rune DSL - the choice data type - has been used extensively for the asset refactoring in CDM 6.
Example of new items defined as choice types include:
AssetInstrument
In addition, some fundamental data types previously defined using a one-of condition have been updated to choice types. Compared to the regular one-of condition, choice types force each of the choice options to have single cardinality.
Product: defined as a choice betweenTransferableProduct(which extendsAsset) andNonTransferableProduct(renamed fromContractualProduct, previously included inProduct). Other data types previously included inProductare now defined asAssetorObservablechoices instead:Commodity: now extendsAssetBasenotProductBase.- Accordingly,
productTaxonomyhas been replaced bytaxonomyand the conditions updated.
- Accordingly,
SecurityandLoan: now extendInstrumentBasenotProductBase.Basket: now extendsAssetBasenotProductBase.BasketConstituentnow extendsObservablenotProduct.- Moved from the
productnamespace to theobservablenamespace.
Index: now extendsIndexBasenotProductBaseForeignExchangehas been marked as deprecated.- The deprecated
ExchangeRateandCrossRatedata types have both been deleted.
- The deprecated
AssetPool: removed (it was previously introduced from FpML but has been found to be incorrect and unusable).- Removed the reference to
AssetPoolfromProduct.
- Removed the reference to
Observable: defined as a choice betweenAsset,IndexandBasket. In addition, the following attributes have been removed fromObservable:Commodity: now available directly as anAsset.QuotedCurrencyPair: replaced by the the FX observable data type insideIndex.- The unused attribute
optionReferenceTypeand its corresponding enumeratorOptionReferenceTypeEnumhave been removed from the model.
FloatingRateOption: renamed asInterestRateIndex, and updated to be a choice betweenFloatingRateIndexandInflationIndex.- Update the
rateOptionattribute onFloatingRateBaseto be of typeInterestRateIndex, since it is used for both floating and inflation indices. - The following two functions have been moved from the
cdm.observable.asset.fronamespace to thecdm.observable.assetnamespace, as they act on an interest rate index and not just a floating rate index:IndexValueObservationIndexValueObservationMultiple
- Update the
Payout: defined as a choice between different types of payout. Because some payout types were previously defined with multiple cardinality, attributes using thePayouttype (for example inEconomicTermsorResetInstruction) now have multiple cardinality. Also removed fromPayout:SecurityPayout: deleted type.Cashflow: use in theForeignExchangedata type also deprecated.ForwardPayout: renamed toSettlementPayoutand usage broadened to cover the settlement of any underlier, whether on a current date or forward basis, for either physical or cash settlement.
All references to choice types need to be updated because they are now treated as Capitalised Data Types rather than lower case attributes. For example, a previous reference might have read:
payout -> interestRatePayout -> floatingAmount
and must now be written as:
payout -> InterestRatePayout -> floatingAmount
This capitalisation also applies to the CDM's serialisation format (JSON).
Other data type and attribute changes
- Tradable product:
TradeextendsTradableProductinstead of containing it as an attribute.- The
productattribute inTradableProductcan only be aNonTransferableProduct(previously it could be anyProduct).
- Removed the following deprecated data types used in the Product Model:
BondConvertibleBondEquityIdentifiedProductObservationSourceSecurityPayout- Also removed the functions which act upon
SecurityPayout.
- Also removed the functions which act upon
- Removed the following deprecated data types related to the deprecated
SecurityPayout:SecurityLegInitialMarginInitialMarginCalculationSecurityValuationSecurityValuationModelBondValudationModelBondPriceAndYieldModelCleanOrDirtyPriceCleanPriceRelativePriceBondEquityModelBondChoiceModelUnitContractValuationModel.
- Refactoring of
ObservationTerms:- The two attributes
pricingTimeandpricingTimeTypeonObservationTermshave been renamedobservationTimeandobservationTimeType, respectively.
- The two attributes
- Changes to
Transfer:- The modelling of
Transferhas been refactored to act uponAssetrather thanObservable, in line with the definition ofAssetas something that can be transferred. TransferBasehas been deleted from the model and replaced byAssetFlowBase, which is also extended by theCashflowtype.
- The modelling of
- Refactored eligible collateral
AssetCriteriaandIssuerCriteriahave been replaced by a refactored and combinedCollateralCriteria.- The
qualifierattribute has been removed fromAgencyRatingCriteria, as it is now redundant. - The data type
ListingTypehas been removed.
- Security finance:
- Rename
RepoTypeEnumtoAssetPayoutTradeTypeEnum. - Rename the
repoTypeattribute totradeTypeonAssetPayout.
- Rename
Sample Impact
The changes listed above have significant impact to serialised data when the CDM is represented in JSON. All of the impacted sample files in the FINOS CDM distribution have been updated accordingly.
The following examples are shown here to illustrate these changes:
1. Impact of the refactoring of the Trade - TradableProduct - EconomicTerms hierarchy
This example is of a vanilla interest rate swap. In CDM 5, the structure appeared as follows:
{
  "trade" : {
    "tradableProduct" : {
      "product" : {
        "contractualProduct" : {
          "productTaxonomy" : [ {
            "source" : "ISDA",
            "productQualifier" : "InterestRate_IRSwap_FixedFloat"
          } ],
          "economicTerms" : {
            "payout" : {
              "interestRatePayout" : [ {
                "payerReceiver" : {
                }
          } ] } }
} } } } }
In CDM 6,
- tradableProduct and contractualProduct no longer appear as they have been collapsed into
product - productTaxonomy is now just
Taxonomy InterestRatePayoutis capitalised as it is now a choice data type
These differences can be seen in this sample:
{
  "trade" : {
    "product" : {
      "taxonomy" : [ {
        "source" : "ISDA",
        "productQualifier" : "InterestRate_IRSwap_FixedFloat"
      } ],
      "economicTerms" : {
        "payout" : [ {
          "InterestRatePayout" : {
            "payerReceiver" : {
	    }
} } ] } } } }
2. Example of a foreign exchange contract using a SettlementPayout
In CDM 5, foreign exchange was represented using a Forward Payout containing a Foreign Exchange underlier (some terms omitted for clarity):
{
  "trade" : {

    "tradableProduct" : {
      "product" : {
        "contractualProduct" : {
          "productTaxonomy" : [ {
            "source" : "ISDA",
            "productQualifier" : "ForeignExchange_Spot_Forward"
          } ],
          "economicTerms" : {
            "payout" : {
              "forwardPayout" : [ {
                "settlementTerms" : {
                  "settlementDate" : {
                    "valueDate" : "2001-10-25",
                },
                "underlier" : {
                  "foreignExchange" : {
                    "exchangedCurrency1" : {

                      },
                      "priceQuantity" : {

                        }
                    },
                    "exchangedCurrency2" : {

                      },
                      "priceQuantity" : {

                        }
                    }
} } ] } } } } } } }
In CDM 6, these trades are represented using a SettlementPayout where the underlier is a cash asset:
{
  "trade" : {
    "product" : {
      "taxonomy" : [ {
        "source" : "ISDA",
        "productQualifier" : "ForeignExchange_Spot_Forward"
      } ],
      "economicTerms" : {
        "payout" : [ {
          "SettlementPayout" : {

            "settlementTerms" : {
              "settlementDate" : {
                "valueDate" : "2001-10-25"
              }
            },
            "underlier" : {
              "Observable" : {
                "address" : {
                  "scope" : "DOCUMENT",
                  "value" : "observable-1"
                }
} } } } ] } } } }
The second currency reflected in the tradeLot:
{
   "tradeLot" : [ {
      "priceQuantity" : [ {
        "price" : [ {
          "value" : {
            "value" : 1.48,
            "unit" : {
              "currency" : {
                "value" : "USD"
              }
            },
            "perUnitOf" : {
              "currency" : {
                "value" : "GBP"
              }
            },
            "priceType" : "ExchangeRate"
          }
        } ],
        "quantity" : [ {
          "value" : {
            "value" : 10000000,
            "unit" : {
              "currency" : {
                "value" : "GBP"
              }
            }
          }
        }, {
          "value" : {
            "value" : 14800000,
            "unit" : {
              "currency" : {
                "value" : "USD"
              }
            }
          }
        } ],
        "observable" : {
          "value" : {
            "Asset" : {
              "Cash" : {
                "identifier" : [ {
                  "identifier" : {
                    "value" : "GBP"
                  },
                  "identifierType" : "CurrencyCode"
                } ]
              }
            }
          }
} } ] } ] }
3. Securities Financing
CDM 5 treated both repos and securities lending trades in a similar manner and was unable to differentiate between the two in product qualification.
The modelling typically:
- qualified all securities financing products as "SecuritiesFinance"
- consisted of a
ContractualProductwith a singleInterestRatePayoutin theEconomicTerms - used a
Collateralobject with anAssetPayoutfor the security being either repurchased or lent.
Sample (some terms omitted for clarity):
{
  "trade" : {

    "tradableProduct" : {
      "product" : {
        "contractualProduct" : {
          "productTaxonomy" : [ {
            "source" : "ISDA",
            "productQualifier" : "SecuritiesFinance"
          } ],
          "economicTerms" : {
            "effectiveDate" : {

            },
            "terminationDate" : {
            },
            "payout" : {
              "interestRatePayout" : [ {
                "payerReceiver" : {
                  "payer" : "Party1",
                  "receiver" : "Party2"
                }

} ] } } } } } } }
with Collateral (some terms omitted for clarity):
{
  "collateral" : {
    "collateralPortfolio" : [ {
      "value" : {
        "collateralPosition" : [ {
          "product" : {
            "contractualProduct" : {
              "economicTerms" : {
                "payout" : {
                  "assetPayout" : [ {
                    "payerReceiver" : {
                      "payer" : "Party1",
                      "receiver" : "Party2"
                    },
                    "assetLeg" : [ {
                      "settlementDate" : {

                          },
                      "deliveryMethod" : "DeliveryVersusPayment"
                    }, {
                    "securityInformation" : {
                      "security" : {
                        "productIdentifier" : [ {
                          "value" : {
                            "identifier" : {
                              "value" : "ST001"
                            },
                            "source" : "SEDOL",
                            "meta" : {
                              "globalKey" : "970a835f"
                            }
                          }
                        } ],
                        "securityType" : "Equity"
                       }
} } ] } ] } } } } } ] } } ] } }
3.1 Example of a Repurchase Agreement
CDM 6 offers enhanced support for repurchase agreements, replacing the implementation of securities financing in section 3 above. A repurchase agreement:
- qualifies as "RepurchaseAgreement"
- is composed of a
Producta singleInterestRatePayoutin theEconomicTermsto represent the principal payment - and a
Collateraldefinition with aTransferableProductfor the asset being exchanged
Example of the product structure (some terms omitted for clarity):
{
  "trade" : {
    "product" : {
      "taxonomy" : [ {
        "source" : "ISDA",
        "productQualifier" : "RepurchaseAgreement"
      } ],
      "economicTerms" : {
        "effectiveDate" : {

          }
        },
        "terminationDate" : {

        },
        "payout" : [ {
          "InterestRatePayout" : {
            "payerReceiver" : {
              "payer" : "Party1",
              "receiver" : "Party2"
            },
            "priceQuantity" : {

            },
            "principalPayment" : {
              "initialPayment" : true,
              "finalPayment" : true,
              "intermediatePayment" : false,
              "meta" : {
                "globalKey" : "12a6f5"
              }
            },
            "rateSpecification" : {
              "FixedRateSpecification" : {
                "rateSchedule" : {
                  "price" : {

                  }
} } } } } ] } } }
and the collateral structure:
{
  "collateral" : {
    "collateralPortfolio" : [ {
      "value" : {
        "collateralPosition" : [ {
          "product" : {
            "TransferableProduct" : {
              "Instrument" : {
                "Security" : {
                  "identifier" : [ {
                    "identifier" : {
                      "value" : "GB00B24FF097"
                    },
                    "identifierType" : "ISIN"
                  } ]
                }
              }
} } } ] } } ] } }
3.2 Example of a Securities Lending trade
CDM 6 offers enhanced support for securities lending, replacing the implementation of securities financing in section 3 above. Securities Lending trades are represented:
- using a product that qualifies as "SecurityLending"
- composed of Economic Terms with a single
AssetPayoutwith aSecurityunderlier for the asset being lent - with the cash payment modelled within a
Collateralobject with a transferable product composed of aCashasset with anInterestRatePayout.
A non-cash collateral trade would have aCollateraldefinition with aTransferableProductfor the asset(s) being used as collateral.
This can be seen in this sample (some items omitted for clarity):
{
  "product" : {
    "taxonomy" : [ {
      "source" : "ISDA",
      "productQualifier" : "SecurityLending"
    } ],
    "economicTerms" : {
      "effectiveDate" : {

      },
      "terminationDate" : {

        }
      },
      "payout" : [ {
        "AssetPayout" : {
          "payerReceiver" : {

          },
          "priceQuantity" : {

          },
          "assetLeg" : [ {
            "settlementDate" : {
              "adjustableDate" : {

                },
                "adjustedDate" : {
                  "value" : "2020-09-22"
            },
            "deliveryMethod" : "DeliveryVersusPayment"
          },
          "underlier" : {
            "Instrument" : {
              "Security" : {
                "identifier" : [ {
                  "identifier" : {
                    "value" : "ST001"
                  },
                  "identifierType" : "SEDOL"
                } ],
                "instrumentType" : "Equity"
              }
            }
          }

      } ],
      "collateral" : {
        "collateralPortfolio" : [ {
          "value" : {
            "collateralPosition" : [ {
              "product" : {
                "TransferableProduct" : {
                  "Cash" : {
                    "identifier" : [ {
                      "identifier" : {
                        "value" : "USD"
                      },
                      "identifierType" : "CurrencyCode"
                    } ]
                  },
                  "economicTerms" : {
                    "payout" : [ {
                      "InterestRatePayout" : {

                        },
                        "priceQuantity" : {
                          "quantitySchedule" : {

                          }
} } ] } } } } ] } } ] } } } ] } }
Option Payout refactoring
Data types and enumeration changes
- Removed
OptionStyletype and the three option exercise types contained inside it:AmericanExercise,EuropeanExercise,BermudaExercise. - Replaced these with new
OptionExerciseStyleEnumenumeration with valuesAmerican,EuropeanandBermuda. - Removed
OptionExercisetype. - Replaced these with new
ExerciseTermstype, containing:- all of the distinct attributes present before in
AmericanExercise,EuropeanExercise, andBermudaExercisetypes, - a
styleattribute of typeOptionExerciseStyleEnum, - and the
exerciseProcedureattribute of typeExerciseProcedurethat was previously contained inOptionExercise.
- all of the distinct attributes present before in
- Switched
exerciseTermsattribute inOptionPayouttype to use the newExerciseTermstype instead of the removedOptionExercisetype. - Moved the
strikeattribute previously contained inOptionExercisetype toOptionPayouttype. - Removed
americanExercise,europeanExercise, andbermudaExerciseattributes fromCancelableProvision,ExtendibleProvision, andOptionalEarlyTerminationtypes.
Sample Impact
There are many samples impacted by this change, namely all the samples utilizing the OptionPayout structure. The impact on the three following samples (one European, one American, one Bermuda) is shown to visualize how the refactoring of the OptionPayout affects the structure of the CDM trades:
eqd ex04 european call index long form: theOptionStylehas been removed in favor of the thestyle= "European", and the relevant fields previously undereuropeanExercise(expirationDateandexpirationTimeType). Additionally, thestrikeis moved from insideexerciseTermsto outside.
From:
"optionPayout": [
    {
        ...
        "exerciseTerms": {
            "optionStyle": {
                "europeanExercise": {
                    "expirationDate": [
                        {
                            "adjustableDate": {
                                "unadjustedDate": "2004-12-19",
                                "dateAdjustments": {
                                    "businessDayConvention": "NONE"
                                }
                            }
                        }
                    ],
                    "expirationTimeType": "OSP"
                }
            },
            "strike": {
                "strikePrice": {
                    "value": 8700,
                    "unit": {
                        "currency": {"value": "CHF"}
                    },
                    "perUnitOf": {"financialUnit": "IndexUnit"},
                    "priceType": "AssetPrice"
                }
            },
            "exerciseProcedure": {
                "automaticExercise": {"isApplicable": true}
            }
        },
        ...
    }
]
To this:
"optionPayout": [
    {
        ...
        "exerciseTerms": {
            "style": "European",
            "expirationDate": [
                {
                    "adjustableDate": {
                        "unadjustedDate": "2004-12-19",
                        "dateAdjustments": {
                            "businessDayConvention": "NONE"
                        }
                    }
                }
            ],
            "expirationTimeType": "OSP",
            "exerciseProcedure": {
                "automaticExercise": {"isApplicable": true}
            }
        },
        "strike": {
            "strikePrice": {
                "value": 8700,
                "unit": {
                    "currency": {"value": "CHF"}
                },
                "perUnitOf": {"financialUnit": "IndexUnit"},
                "priceType": "AssetPrice"
            }
        }
    }
]
eqd ex01 american call stock long form: theOptionStylehas been removed in favor of the thestyle= "American", and the relevant fields previously underamericanExercise(commencementDate,expirationDate,latestExerciseTime,expirationTimeType, andmultipleExercise). Additionally, thestrikeis moved from insideexerciseTermsto outside.
From:
"optionPayout": [
    {
        ...
        "exerciseTerms": {
            "optionStyle": {
                "americanExercise": {
                    "commencementDate": {
                        "adjustableDate": {
                            "unadjustedDate": "2001-07-13",
                            "dateAdjustments": {
                                "businessDayConvention": "NONE"
                            }
                        }
                    },
                    "expirationDate": {
                        "adjustableDate": {
                            "unadjustedDate": "2005-09-27",
                            "dateAdjustments": {
                                "businessDayConvention": "NONE"
                            }
                        }
                    },
                    "latestExerciseTime": {
                        "hourMinuteTime": "17:15:00",
                        "businessCenter": {"value": "GBLO"}
                    },
                    "expirationTimeType": "Close",
                    "multipleExercise": {
                        "integralMultipleAmount": 1,
                        "minimumNumberOfOptions": 1,
                        "maximumNumberOfOptions": 150000
                    }
                }
            },
            "strike": {
                "strikePrice": {
                    "value": 32.00,
                    "unit": {
                        "currency": {"value": "EUR"}
                    },
                    "perUnitOf": {"financialUnit": "Share"},
                    "priceType": "AssetPrice"
                }
            },
            "exerciseProcedure": {
                "automaticExercise": {"isApplicable": true}
            }
        }
        ...
    }
]
To this:
"optionPayout": [
    {
        ...
        "exerciseTerms": {
            "style": "American",
            "commencementDate": {
                "adjustableDate": {
                    "unadjustedDate": "2001-07-13",
                    "dateAdjustments": {
                        "businessDayConvention": "NONE"
                    }
                }
            },
            "expirationDate": [
                {
                    "adjustableDate": {
                        "unadjustedDate": "2005-09-27",
                        "dateAdjustments": {
                            "businessDayConvention": "NONE"
                        }
                    }
                }
            ],
            "latestExerciseTime": {
                "hourMinuteTime": "17:15:00",
                "businessCenter": {"value": "GBLO"}
            },
            "expirationTimeType": "Close",
            "multipleExercise": {
                "integralMultipleAmount": 1,
                "minimumNumberOfOptions": 1,
                "maximumNumberOfOptions": 150000
            },
            "exerciseProcedure": {
                "automaticExercise": {"isApplicable": true}
            }
        },
        "strike": {
            "strikePrice": {
                "value": 32.00,
                "unit": {
                    "currency": {"value": "EUR"}
                },
                "perUnitOf": {"financialUnit": "Share"},
                "priceType": "AssetPrice"
            }
        }
    }
]
ird ex14 berm swaption: theOptionStylehas been removed in favor of the thestyle= "Bermuda", and the relevant fields previously underbermudaExercise(bermudaExerciseDates,relevantUnderlyingDate,earliestExerciseTime, andexpirationTime).
From:
"optionPayout": [
    {
        ...
        "exerciseTerms": {
            "optionStyle": {
                "bermudaExercise": {
                    "bermudaExerciseDates": {
                        "adjustableDates": {
                            "unadjustedDate": [
                                "2000-12-28",
                                "2001-04-28",
                                "2001-08-28"
                            ],
                            "dateAdjustments": {
                                "businessDayConvention": "FOLLOWING",
                                "businessCenters": {
                                    "businessCenter": [
                                        {"value": "EUTA"},
                                        {"value": "GBLO"}
                                    ]
                                }
                            }
                        }
                    },
                    "relevantUnderlyingDate": {
                        "relativeDates": {
                            "periodMultiplier": 2,
                            "period": "D",
                            "dayType": "Business",
                            "businessDayConvention": "NONE",
                            "businessCenters": {
                                "businessCenter": [
                                    {"value": "EUTA"},
                                    {"value": "GBLO"}
                                ]
                            },
                            "dateRelativeTo": {
                                "globalReference": "32e3a858",
                                "externalReference": "bermudaExercise0"
                            }
                        }
                    },
                    "earliestExerciseTime": {
                        "hourMinuteTime": "09:00:00",
                        "businessCenter": {"value": "BEBR"}
                    },
                    "expirationTime": {
                        "hourMinuteTime": "11:00:00",
                        "businessCenter": {"value": "BEBR"}
                    },
                    "meta": {
                        "globalKey": "32e3a858",
                        "externalKey": "bermudaExercise0"
                    }
                }
            },
            "exerciseProcedure": {
                "manualExercise": {
                    "exerciseNotice": {
                        "exerciseNoticeGiver": "Seller",
                        "businessCenter": {"value": "GBLO"}
                    }
                },
                "followUpConfirmation": true
            }
        }
        ...
    }
]
To this:
"optionPayout": [
    {
        ...
        "exerciseTerms": {
            "style": "Bermuda",
            "exerciseDates": {
                "adjustableDates": {
                    "unadjustedDate": [
                        "2000-12-28",
                        "2001-04-28",
                        "2001-08-28"
                    ],
                    "dateAdjustments": {
                        "businessDayConvention": "FOLLOWING",
                        "businessCenters": {
                            "businessCenter": [
                                {"value": "EUTA"},
                                {"value": "GBLO"}
                            ]
                        }
                    }
                }
            },
            "relevantUnderlyingDate": {
                "relativeDates": {
                    "periodMultiplier": 2,
                    "period": "D",
                    "dayType": "Business",
                    "businessDayConvention": "NONE",
                    "businessCenters": {
                        "businessCenter": [
                            {"value": "EUTA"},
                            {"value": "GBLO"}
                        ]
                    },
                    "dateRelativeTo": {
                        "globalReference": "5c12e2ce",
                        "externalReference": "bermudaExercise0"
                    }
                }
            },
            "earliestExerciseTime": {
                "hourMinuteTime": "09:00:00",
                "businessCenter": {"value": "BEBR"}
            },
            "expirationTime": {
                "hourMinuteTime": "11:00:00",
                "businessCenter": {"value": "BEBR"}
            },
            "exerciseProcedure": {
                "manualExercise": {
                    "exerciseNotice": {
                        "exerciseNoticeGiver": "Seller",
                        "businessCenter": {"value": "GBLO"}
                    }
                },
                "followUpConfirmation": true
            },
            "meta": {
                "globalKey": "5c12e2ce",
                "externalKey": "bermudaExercise0"
            }
        }
    }
]
Misc. renaming or deletion
- RBA Bond Basis
- Replaced the codes
RBA_BOND_BASIS_QUARTER,RBA_BOND_BASIS_SEMI_ANNUALandRBA_BOND_BASIS_ANNUALwith the codeRBA_BOND_BASISinDayCountFractionEnum. - Mapping added to populate the new code from the FpML code
RBA.
- Replaced the codes
- Portfolio Return Terms
- Removed
[deprecated]attributes below from typePriceReturnTerms:valuationPriceInitialvaluationPriceFinal
- Replaced by existing attributes in
PerformancePayout:initialValuationPricefinalValuationPrice
- Renamed attributes in
ValuationDates:initialValuationDateinstead ofvaluationDatesInitialinterimValuationDateinstead ofvaluationDatesInterimfinalValuationDateinstead ofvaluationDatesFinal
- Updated
Baskettype:- Renamed
portfolioBasketConstituentof typeBasketConstituentas simplybasketConstituent. - Removed
[deprecated]basketConstituentattribute, previously of typeProduct.
- Renamed
- Removed
- Natural person
- Removed the
personRoleattribute of typeNaturalPersonRolefromNaturalPerson. - Replaced by existing
personRoleattribute inParty.
- Removed the
Misc. data validation changes
- Exotic Equity Products and Exercise Terms validation conditions
- Attribute
expirationTimerelaxed to be optional (previously mandatory). - Attribute
expirationTimeTypetightened to be mandatory (previously optional). - Addition of validation condition
ExpirationTimeChoiceto establish the correlation betweenexpirationTimeandexpirationTimeType. - Affected samples have been updated to ensure that
expirationTimeTypeis populated asSpecificTimewhen theexpirationTimeattribute is populated. See for example:fpml-5-13 > fx-ex09-euro-opt.
- Attribute